Business tax accounting statements provide a complete financial picture of your company’s performance, tax obligations, and overall health. To read tax accounting statements effectively, focus on three core documents: the balance sheet, income statement, and cash flow statement. Each reveals different aspects of your financial position, and together they form the foundation for smart business decisions and accurate tax filing.
Many business owners receive these statements from their accountant or bookkeeper but struggle to extract meaningful insights from the numbers. The ability to interpret these documents transforms you from a passive observer into an active participant in your company’s financial strategy. Once you understand what each line item represents and how the statements connect, you gain the power to spot trends, identify problems early, and plan for growth.
Why Financial Statements Matter More Than Tax Returns Alone
Your tax return shows what you owe the IRS, but your financial statements tell the complete story of your business operations throughout the year. Tax returns are backward-looking compliance documents, while properly maintained accounting statements serve as management tools that inform daily decisions.
The balance sheet captures your company’s financial position at a specific moment. It lists everything you own (assets), everything you owe (liabilities), and what remains for the owners (equity). Think of it as a financial snapshot frozen in time, typically at the end of a month, quarter, or year.
The income statement, sometimes called a profit and loss statement, measures performance over a period. It subtracts all expenses from all revenue to calculate your net profit or loss. This document answers the fundamental question: did we make money or lose money during this time frame?
Breaking Down the Balance Sheet Line by Line
Assets appear first on a balance sheet, typically divided into current and long-term categories. Current assets include cash, accounts receivable (money customers owe you), inventory, and prepaid expenses. These items will convert to cash or be used within one year.
Long-term assets include property, equipment, vehicles, and intangible items like patents or trademarks. The balance sheet shows both the original cost and accumulated depreciation, which spreads the expense of these assets over their useful life for tax purposes.
Liabilities follow the same current and long-term structure. Current liabilities include accounts payable (bills you owe suppliers), short-term loans, payroll obligations, and taxes due within the year. Long-term liabilities cover mortgages, equipment loans, and other debts extending beyond 12 months.
Equity represents the difference between total assets and total liabilities. For corporations, this includes stock and retained earnings. For sole proprietors and partnerships, it reflects owner contributions and accumulated profits. The fundamental accounting equation, Assets = Liabilities + Equity, must always balance perfectly.
Understanding Income Statement Components
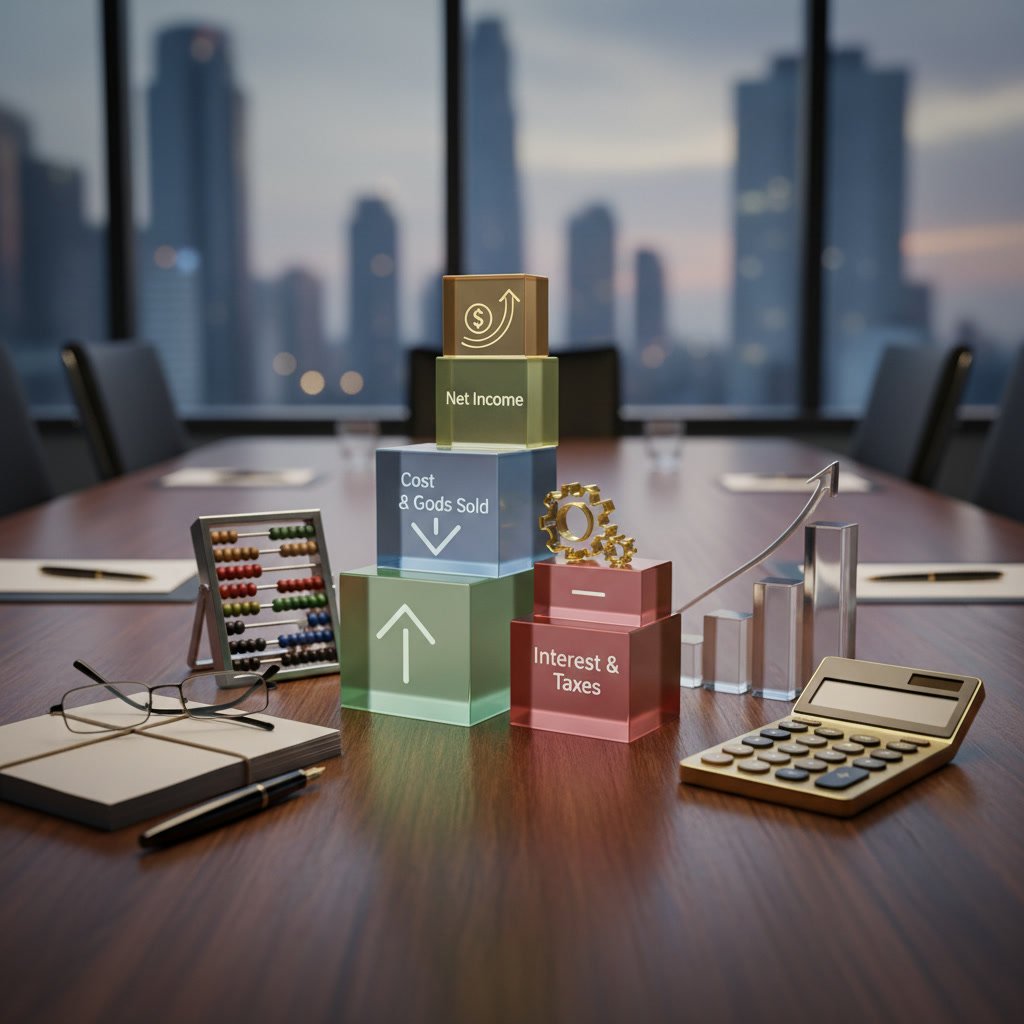
Revenue sits at the top of the income statement. For product-based businesses, cost of goods sold appears next, representing the direct costs of producing or purchasing inventory. Subtracting cost of goods sold from revenue yields gross profit, a critical metric that reveals how much money remains to cover operating expenses.
Operating expenses include rent, salaries, utilities, marketing, insurance, and professional fees. These costs keep your business running but do not directly tie to producing specific units of product or service. Professional bookkeeping ensures these expenses are categorized correctly for both management reporting and tax optimization.
Subtracting operating expenses from gross profit produces operating income, which shows profit from core business activities before interest and taxes. Below this line, you will find interest expense, other income or expenses, and finally the income tax expense, leading to net income at the bottom.
The Cash Flow Statement Reveals True Liquidity
The cash flow statement often receives less attention than the other two, but it answers the most urgent question many business owners face: why does my bank account not match my reported profit? This statement reconciles net income with actual cash movement.
Cash flow divides into three categories. Operating activities adjust net income for non-cash items like depreciation and changes in working capital such as receivables and payables. Investing activities track purchases or sales of long-term assets. Financing activities record borrowing, loan repayments, and owner contributions or distributions.
A profitable company can still run out of cash if customers pay slowly, inventory ties up funds, or rapid growth demands constant investment. The cash flow statement exposes these dynamics before they become crises. Understanding this document is particularly important when exploring business funding options, as lenders scrutinize cash flow carefully.
Key Ratios That Simplify Complex Statements
Financial ratios convert raw numbers into meaningful comparisons. The current ratio divides current assets by current liabilities to measure short-term financial health. A ratio above 1.0 indicates you have enough liquid resources to cover immediate obligations. Most healthy businesses maintain a current ratio between 1.5 and 3.0.
The debt-to-equity ratio compares total liabilities to total equity. Higher ratios indicate more leverage and financial risk. Industry standards vary widely, but understanding your position helps when negotiating loans or planning expansions.
Gross margin percentage (gross profit divided by revenue) shows how efficiently you convert sales into profit before operating costs. Tracking this monthly helps identify pricing problems, rising supplier costs, or inventory shrinkage. A declining gross margin demands immediate investigation.
Net profit margin (net income divided by revenue) reveals the percentage of each sales dollar that reaches the bottom line. This ratio enables comparison across time periods and against industry benchmarks, regardless of company size.
Common Statement Reading Mistakes Florida Business Owners Make
Many entrepreneurs focus exclusively on the bottom line of the income statement, ignoring the balance sheet entirely. This creates blind spots around growing receivables, aging inventory, or accumulating debt. All three statements work together, and each tells part of the complete financial story.
Another frequent error involves confusing cash with profit. Accrual accounting, which most businesses use, records revenue when earned and expenses when incurred, not when cash changes hands. A large sale might boost your income statement this month even though the customer will not pay for 60 days. Your bank account tells a different story than your profit and loss.
Some business owners also overlook the distinction between personal and business finances, particularly in sole proprietorships and single-member LLCs. Proper financial statements separate business operations from personal transactions, creating clarity essential for tax compliance and growth planning. Quick Tax and Credit Solutions Texas works with business owners across Florida to establish clean accounting practices that support both operational management and tax strategy.
How to Spot Red Flags in Your Financial Statements
Certain patterns signal trouble before it becomes obvious in your bank account. Rising accounts receivable as a percentage of sales suggests collection problems. If your customers are paying more slowly, your cash flow will suffer even as revenue appears healthy on paper.
Inventory that grows faster than sales indicates you are stocking products that are not moving. This ties up cash and increases the risk of obsolescence or spoilage. Compare inventory turnover rates monthly to catch this problem early.
A declining gross margin deserves immediate attention. Suppliers may have raised prices, employees might be giving unauthorized discounts, or theft could be occurring. Whatever the cause, shrinking gross profit threatens your ability to cover fixed operating expenses.
Watch for negative trends in accounts payable. If you are stretching payment terms with suppliers due to cash shortages, the balance sheet will show growing payables even as your income statement reports profit. This mismatch indicates a cash flow problem that could damage vendor relationships.
Using Statements for Tax Planning Throughout the Year
Monthly financial statements enable proactive tax planning rather than year-end surprises. If your income statement shows strong profits midyear, you have time to discuss strategies with your tax advisor, such as equipment purchases that qualify for Section 179 expensing or increased retirement plan contributions.
The balance sheet reveals opportunities for tax optimization as well. Accumulated depreciation schedules help identify assets fully depreciated for tax purposes but still in service. Strategic replacement timing can maximize deductions. Similarly, reviewing prepaid expenses and accrued liabilities ensures you are taking deductions in the most advantageous year.
Quarterly statement reviews also help estimate tax liability accurately, preventing underpayment penalties. Business owners who understand their statements can make informed estimated tax payments rather than guessing. Professional business tax filling services combine statement analysis with tax code expertise to minimize your annual tax burden legally.
Comparing Your Statements Against Industry Benchmarks
Your financial ratios gain context when compared to industry averages. Trade associations, financial databases, and accounting firms publish benchmark data showing typical performance metrics for businesses in your sector. A 15 percent net margin might be excellent in retail but disappointing in software.
Benchmark comparisons reveal competitive strengths and weaknesses. If your gross margin significantly trails industry norms, you might be paying too much for materials, pricing too low, or operating inefficiently. If your operating expense ratio runs high, you may be overstaffed or spending excessively on overhead.
Year-over-year comparisons of your own statements often prove more valuable than industry benchmarks. Seasonal businesses particularly benefit from comparing the same months across multiple years to identify true trends versus normal fluctuations. Growth trajectories become clear when you line up three or four years of statements side by side.
When to Request Professional Statement Analysis
Complex business structures, multi-state operations, or significant asset holdings demand professional expertise beyond basic statement reading. A qualified accountant can identify optimization opportunities invisible to untrained eyes, such as cost segregation strategies for real estate or inventory accounting method changes that reduce taxes.
Businesses contemplating major decisions like expansions, acquisitions, or ownership changes need thorough financial statement analysis. Professional review validates the numbers, identifies hidden liabilities, and ensures you understand the full financial picture before committing resources. The same applies when preparing to secure financing, as lenders will scrutinize every line item.
Even stable, established businesses benefit from periodic professional reviews. An outside expert brings fresh perspective, catches errors before they compound, and confirms your internal processes produce reliable data. This validation proves particularly valuable if you face an audit or need to present financials to partners or investors. Many business owners discover that understanding outlined in a professional tax accounting review transforms their ability to manage their company strategically.
Building Statement Literacy Into Your Business Routine
Financial statement fluency develops through regular practice, not occasional cramming before tax season. Schedule a monthly review session where you spend 30 minutes examining all three statements. Track three to five key metrics relevant to your business and watch how they trend over time.
Create a simple dashboard that pulls critical numbers from your statements each month: revenue, gross margin, operating expenses, net income, current ratio, and cash balance. Watching these metrics monthly trains your eye to spot abnormalities quickly. When something looks off, you can investigate immediately rather than discovering problems months later.
Ask questions when something on your statements does not make sense. Your bookkeeper or accountant should explain any line item in plain language. If they cannot, the issue may require investigation. The best financial professionals welcome questions because they indicate engaged business ownership.
Consider taking a basic accounting course or working through online tutorials specific to business financial statements. A foundational understanding of debits, credits, and accounting principles removes the mystery and builds confidence. You do not need to become a certified accountant, but grasping the fundamentals transforms statements from confusing paperwork into powerful management tools.
Turning Financial Statements Into Actionable Business Intelligence
Understanding your business tax accounting statements means more than recognizing account names and checking if the numbers balance. It means using those numbers to make better decisions every day. When you spot declining margins, you can renegotiate supplier contracts, adjust pricing, or streamline operations before profits disappear.
When the balance sheet shows cash accumulating beyond operating needs, you can plan strategic investments in equipment, marketing, or expansion. When cash runs tight despite reported profits, you can tighten collection procedures or negotiate better payment terms with suppliers before reaching a crisis point.
The insight you gain transforms financial statements from compliance documents into strategic assets. You will approach tax season with confidence rather than anxiety because you have monitored the numbers all year. You will make expansion decisions based on data rather than gut feeling. Most importantly, you will understand the financial health of your business at a level that separates successful entrepreneurs from those who struggle.
Quick Tax and Credit Solutions Texas has helped business owners across the state build financial literacy and leverage their accounting data for over 20 years. Whether you need help setting up proper bookkeeping systems, interpreting complex statements, or developing tax strategies based on your financial position, experienced guidance makes the difference between simply filing taxes and truly understanding your business finances. Call +1 (214) 647-1669 to schedule a consultation and discover what your financial statements are telling you about your business.